 NO KYC CASINO
Know Your Customer vs Enhanced Due Diligence: Key Differences
Listen, KYC. You know what I mean? Know Your Customer. It's the baseline thing, right. Every casino does it, you gotta do it, government says you gotta know who's throwing money at your tables.
- logged
- by
- Felix Braun
- rail
- Payments
- read
- 3 min
- hash
- 9e72e1f
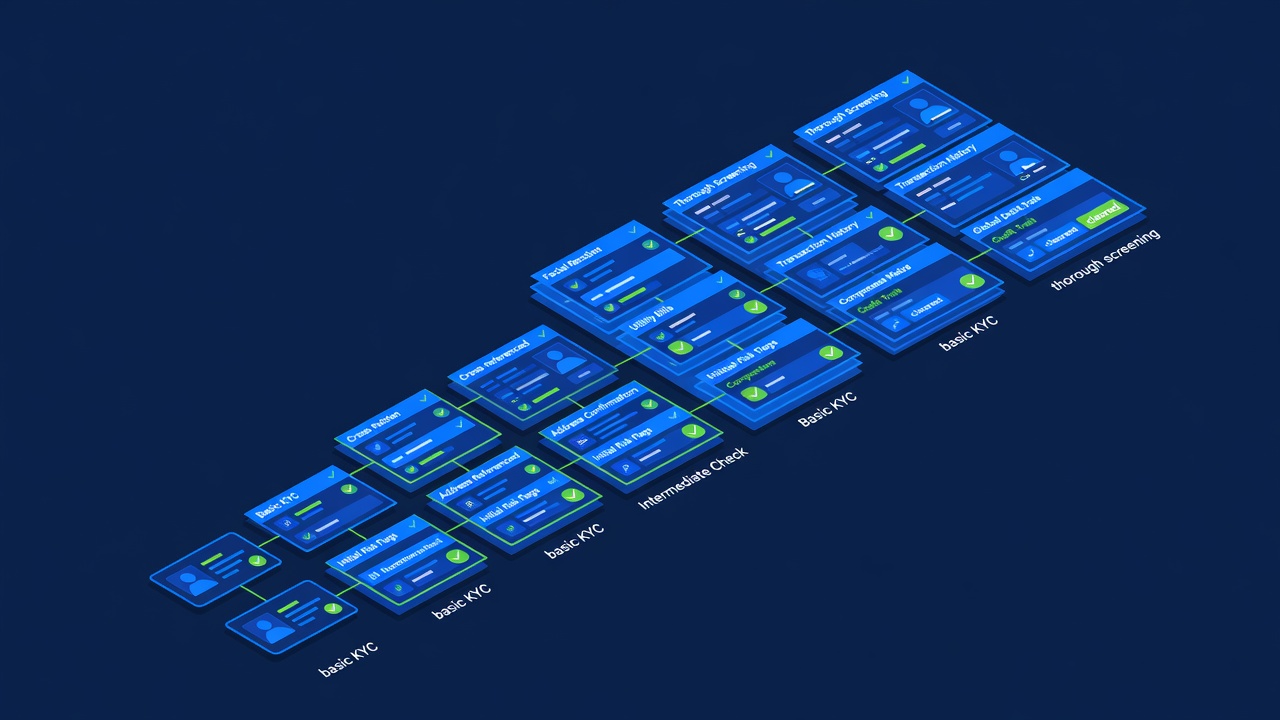
Listen, KYC. You know what I mean? Know Your Customer. It's the baseline thing, right. Every casino does it, you gotta do it, government says you gotta know who's throwing money at your tables. So what is it, really. It's a name, address, phone number, some ID photocopy. That's basically it. You run it through the system, you check if the guy's on a sanctions list, you're done. That's KYC. Pretty straightforward.
Now Enhanced Due Diligence, or EDD, that's the deeper cut. That's when someone's coming in with weird patterns or big money or connections that flag something. So like, a guy walks in, he's got fifty grand cash, he wants to deposit it all at once, wants to play high stakes baccarat for three days straight. That's a flag. KYC was not enough. You now need to dig into where the money came from. And I mean dig. We're talking about financial sources, business background, customer's risk profile.
The Money Laundering Angle
Here's the thing nobody wants to say out loud. Casinos are basically money laundering detection machines if they're doing it right. KYC catches the guy whose name is on a terrorist watch list. Obvious stuff. But money laundering is way more subtle. A guy could have legitimate income sources that are front businesses. So EDD asks questions. Where did this money come from exactly. Can you verify the source. Are there business records. Tax returns. Bank statements going back six months, maybe a year.
The logic is simple if you think about it. If someone's trying to clean money, they're not gonna take it to the casino once a month. They're gonna take it multiple times. Different people maybe. Different amounts, trying to stay below thresholds. That's called structuring and it's a federal crime. So EDD catches it by tracking patterns. The casino's watching for that customer who comes back every week with nine thousand dollars cash.
The Practical Difference
- Initial intake: KYC takes twenty minutes. EDD takes a meeting, maybe a few days of research.
- Documentation: KYC is one ID, one address verification. EDD is birth certificate, tax returns, employment verification, maybe a background check.
- Updates: KYC happens once. EDD is ongoing. You're updating the profile every quarter if the customer's high-risk.
- Cost: KYC costs the casino basically nothing. EDD costs real money. You're paying compliance staff to research. You might pay for background checks from third parties.
- Frequency: KYC applies to everyone. EDD applies to customers above certain thresholds or with suspicious activity.
When EDD Kicks In
So what triggers EDD. Cash transactions over ten thousand. That's automatic in most jurisdictions. Actually, I misspoke. Transactions over ten thousand, you gotta file a Suspicious Activity Report anyway, so EDD is implicit. High-risk jurisdictions, that's another trigger. You got a guy from a country known for financial secrecy, your regulators want to know more about him. Large round numbers. Guy wants to deposit exactly one hundred thousand, that's suspicious because it's round. Legitimate transactions are usually irregular.
The point is this. KYC is the law. EDD is the insurance policy. The casino that only does KYC is legally compliant. The casino that does EDD right survives regulatory audits and doesn't end up with frozen assets.